08-Feb-2025 15:31:12
+91-124-4302020 / 21 / 22 / 23 | +91-7291981124 / 1125 / 1126

 Published on:
A bank auction property can look like an obvious bargain.
You find a property with a reserve price of ?50 lakh when similar
properties in the area appear to be selling for considerably more. The numbers
look attractive, the bank is conducting the auction, and the temptation to bid
can be strong.
But there is one calculation many auction buyers make too late:
The winning bid is not necessarily the actual cost
of acquiring the property.
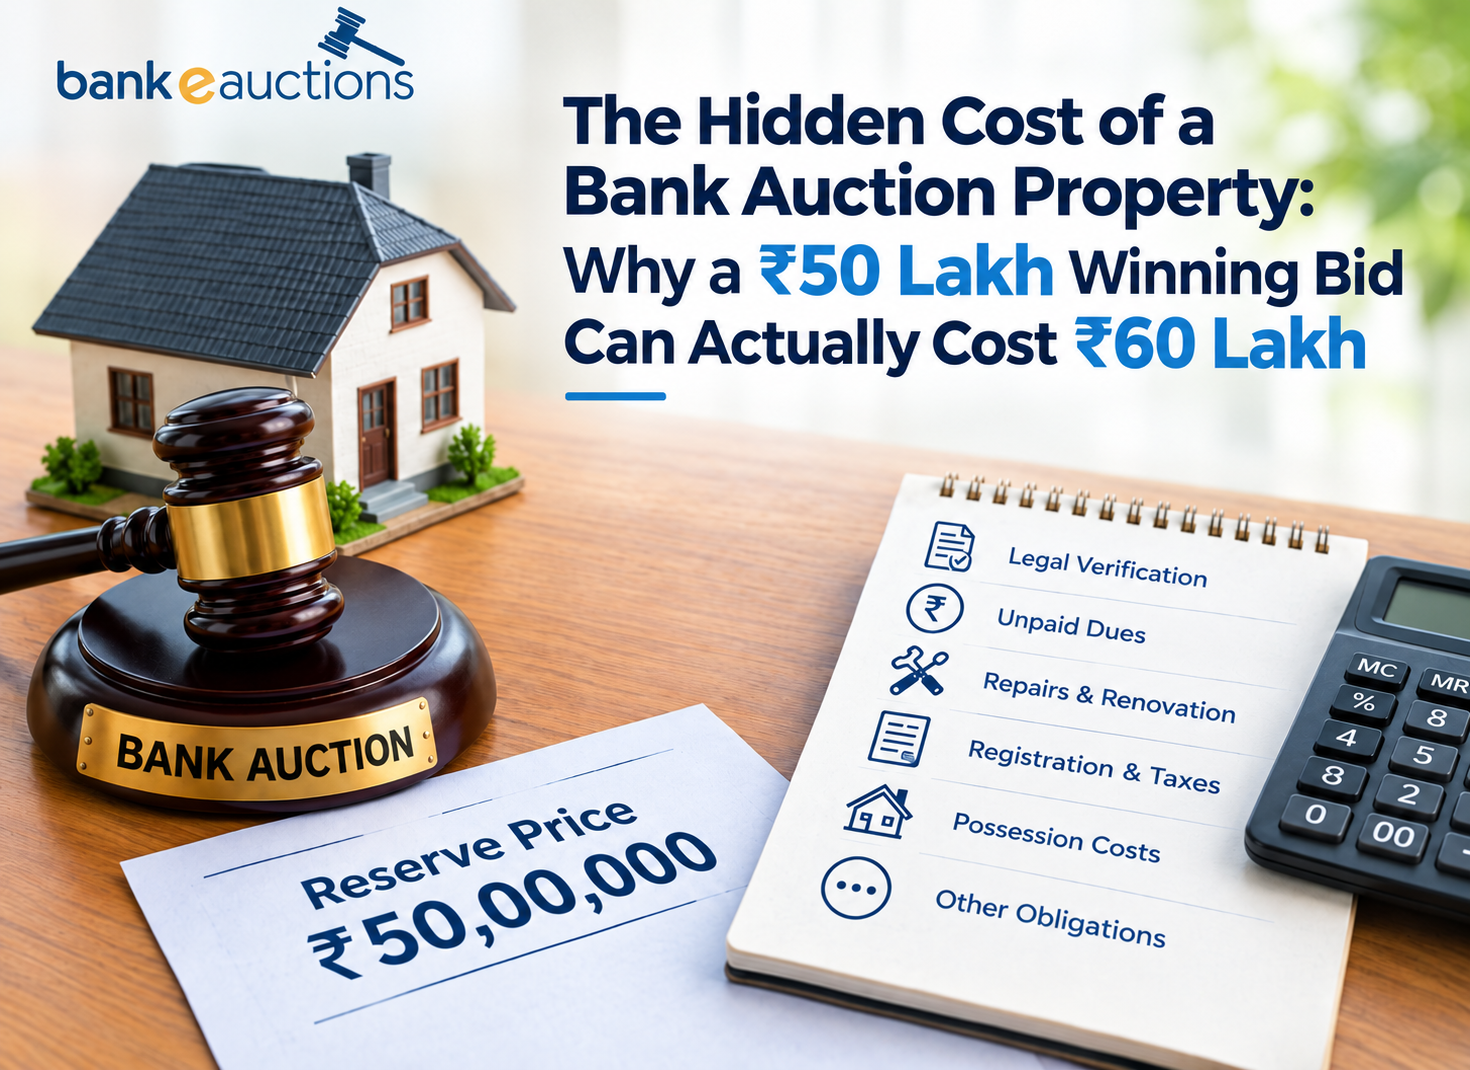
The real cost can include legal verification, unpaid dues, repairs,
registration expenses, possession-related costs and other obligations. This is
why a property that looks inexpensive on the auction portal may not always be
inexpensive after the purchase.
The “True Cost” of
an Auction Property
Before bidding, buyers should stop looking at only the reserve price or
their maximum bid.
Instead, think about the property using this simple formula:
True Acquisition Cost = Winning Bid + Transaction
Costs + Due Diligence + Property Liabilities + Repairs + Possession Costs
Not every property will have every cost, but understanding the complete
picture can prevent an apparently attractive deal from becoming an expensive
mistake.
1. The Winning Bid
Is Only the Starting Point
Suppose you win a property auction for ?50 lakh.
That ?50 lakh is the purchase consideration, but you may still have to
account for applicable stamp duty, registration charges and taxes or compliance
obligations depending on the transaction.
This means your financial planning should begin before you place the
bid—not after you win.
A practical rule is to maintain a separate budget for costs outside the
winning bid.
2. Unpaid Dues Can
Change the Economics
One of the biggest questions before bidding should be:
“What liabilities are attached to this property,
and who will ultimately bear them?”
Depending on the property and auction terms, buyers may need to
investigate property tax, maintenance or society dues, electricity and water
charges, municipal liabilities and other outstanding amounts.
These should not be treated as minor details.
A ?50 lakh property with several lakh rupees of unresolved liabilities
can have a very different economics from a ?50 lakh property with a clean
financial position.
This is why the auction notice and available property information should
be reviewed carefully before bidding.
3. “As Is Where Is”
Means You Need to Think Like an Investor
Auction properties are commonly sold on terms such as “as is where is”
or similar conditions. The exact terms depend on the individual auction notice.
That changes the buyer's mindset.
You are not simply buying a house—you are assessing an asset whose
physical condition may require additional investment.
A property may need:
A discount disappears quickly when repair costs are ignored during
bidding.
4. Possession Has a
Financial Value Too
Another frequently underestimated issue is possession.
A property may have physical possession, symbolic possession or
occupancy-related complications. The exact status should be checked from the
auction documents and verified wherever possible.
If possession is delayed, the buyer may face additional legal,
administrative or holding costs.
For an investor planning to rent or resell the property, every month of
delay can also mean lost potential income.
Therefore, possession status should influence the maximum price you
are willing to bid.
5. Legal Due
Diligence Is Not an Optional Expense
A bank conducting an auction does not mean the buyer should skip
independent verification.
Before bidding, buyers should consider professional verification of the
property's title, ownership history, encumbrances, applicable records, auction
authority and other relevant legal documents.
The objective is simple:
Know exactly what rights you are purchasing before
committing your money.
Spending money on professional due diligence before bidding can be far
cheaper than discovering a serious issue after becoming the successful bidder.
A Better Way to
Decide Your Maximum Bid
Instead of asking:
? ?How much below market value is this property?”
ask:
“What will this property actually cost me after
everything is accounted for?”
For example:
Winning Bid: ?50 lakh
Estimated transaction costs: ?X
Legal due diligence: ?X
Potential dues: ?X
Repairs/renovation: ?X
Possession-related costs: ?X
Only after calculating these numbers should you compare the total with
the property's realistic market value.
This approach turns auction bidding from an emotional decision into an
investment decision.
Where BankeAuctions
Can Help
Finding the right auction opportunity is only the first step. Buyers
need access to auction information, property details and a transparent bidding
process to make better decisions.
BankeAuctions provides a
dedicated digital platform for bank-foreclosed properties and NPA auctions,
connecting financial institutions with prospective buyers. The platform covers
property auctions and also supports auction formats such as DRT and forward
auctions.
The platform allows users to search auction opportunities across
categories and locations, making it easier to identify properties that fit
their requirements.
The Bottom Line
The best auction deal is not necessarily the property with the lowest
reserve price.
It is the property where the total acquisition cost, legal position,
physical condition and possession situation make financial sense.
Before placing your next bid, don't ask only:
? ?What is the auction price?”
Ask:
? ?What will this property really cost me?”
That one question can make the difference between finding a genuine
opportunity and buying an expensive problem.
Leave a Reply